
Private Credit Expands as Peachtree Sees Growing Demand
Feature in Hotelmags.com: Private credit is expanding in hospitality as banks pull back. Peachtree Group sees rising demand and expects continued growth in the sector.

Years of deferred renovations, rising construction costs and more expensive debt are putting pressure on hotel owners. At the same time, limited new supply can make well-located existing properties difficult to replace.
The resulting opportunity is not simply to buy rundown hotels at a discount. It is to find hotels where underlying demand remains strong but the property, ownership structure or financing needs to be reset.
Greg Friedman, CEO of Peachtree Group, and Michael Bernath, SVP of Acquisitions and Dispositions, discussed how investors can distinguish those opportunities from hotels suffering more fundamental impairment.
Several pressures are converging.
Many hotels deferred renovations during and after COVID. Those improvements are increasingly difficult to postpone as brands enforce property improvement requirements and hotels compete for guests.
Renovations have also become more expensive. Bernath estimates that a soft-goods renovation costing roughly $7,000 to $10,000 per key before COVID could cost approximately $20,000 to $25,000 today.
Financing adds another layer.
Limited-service hotel transaction volume reached $23.2 billion in 2021 and $26 billion in 2022, according to figures Bernath cited in the podcast. Some three- to five-year bridge loans associated with that acquisition period are now maturing or have already been extended.
Refinancing into a higher-rate market while simultaneously funding a PIP can require owners to contribute significant additional equity.
As Bernath explains, the distress may therefore reside in the capital stack rather than the hotel.
Physical condition alone does not determine whether a hotel offers value.
Investors need to understand why the hotel is underperforming.
One useful measure is RevPAR index, which compares a hotel’s revenue per available room with its competitive set.
If a hotel historically should outperform its competitive set but has fallen behind because its rooms or common areas are dated, renovation may offer an opportunity to recover market share.
If the hotel and its competitive set are both deteriorating, however, renovations may not solve the underlying problem.
Bernath summarizes the distinction simply: “Not all renovations are created equal from an ROI perspective.”
Hotel capital expenditures can address very different problems.
Guest-facing investments may include rooms, furniture, finishes and other visible improvements. Deferred maintenance may involve mechanical, electrical, plumbing, roofing or other building systems.
Both can be necessary. They do not necessarily offer the same potential return.
As Bernath explains, spending $40,000 per key behind the walls presents a different investment calculation than putting the same amount into cosmetic, guest-facing improvements that may support improved pricing or competitive performance.
Investors therefore need to determine whether CapEx is expected to restore lost competitive position, support higher room rates, meet brand requirements, address deferred maintenance or protect existing performance rather than increase it.
The opportunity in existing hotels is occurring while new supply remains unusually constrained.
Bernath says the current pipeline of actual deliverable hotel assets is below 1%.
High construction and financing costs are part of the reason. As Bernath puts it, “Low supply and high construction costs are the same fact viewed from different directions.”
That environment can benefit existing hotels in markets with durable demand because fewer new properties are entering their competitive sets.
It also helps explain why acquisitions may currently offer a more attractive path than development in many markets, although Bernath continues to see selective development opportunities where demand and supply conditions support new construction.
The Wall Street Journal data referenced Friedman cited showed nationwide hotel sales increasing 28% during the first half of 2026 compared with the same period in 2025.
Bernath, however, cautions that the recovery is uneven.
Luxury and urban full-service hotels have driven much of the increase, while select- and limited-service transaction volume remained down approximately 11% to 12% through the second quarter.
He nevertheless sees catalysts for a more active transaction market as debt maturities, renovations, lender pressure and investor fatigue push more owners toward decisions.
An owner facing expensive refinancing and substantial renovation requirements may sell even when the hotel continues to serve a healthy market.
The amount of CapEx matters less than what it fixes and whether the spending can improve competitive performance.
Buying below replacement cost is useful only in context. Investors still need sustainable demand, an attractive basis and a credible path to improving the property.
An underinvested hotel is a property where renovations, maintenance or other capital expenditures have lagged what is needed to maintain its physical condition, brand standards or competitive position.
A property improvement plan, or PIP, specifies renovations and upgrades required by a hotel brand, often in connection with an ownership change or as part of maintaining franchise standards.
Renovations deferred during and after COVID are becoming harder to postpone, while renovation costs have risen and brands are becoming more assertive about quality requirements.
It depends on the market. Bernath currently sees acquisitions as more compelling broadly because high construction costs and limited financing make many developments difficult to justify. Select markets with limited supply and strong demand can still support new development.
The episode emphasizes durable local demand, competitive-set performance, the nature and cost of required CapEx, acquisition basis and whether distress stems from the hotel itself or its capital structure.
Listen to Peachtree Point of View for Greg Friedman and Michael Bernath’s full discussion of hotel acquisitions, deferred CapEx, limited new supply and how they evaluate value-add opportunities in today’s hospitality market.
Opportunity Zones are entering their second phase. Starting in 2027, the program becomes permanent, capital gains get a rolling five-year deferral instead of a fixed deadline, and rural investments qualify for a larger basis step-up. Zones will also be redesignated every 10 years going forward. These changes make Opportunity Zones easier to fold into long-term investment planning, but they don't change the importance of underwriting the investment itself.
Opportunity Zones will look materially different beginning in 2027. The key changes are summarized below.
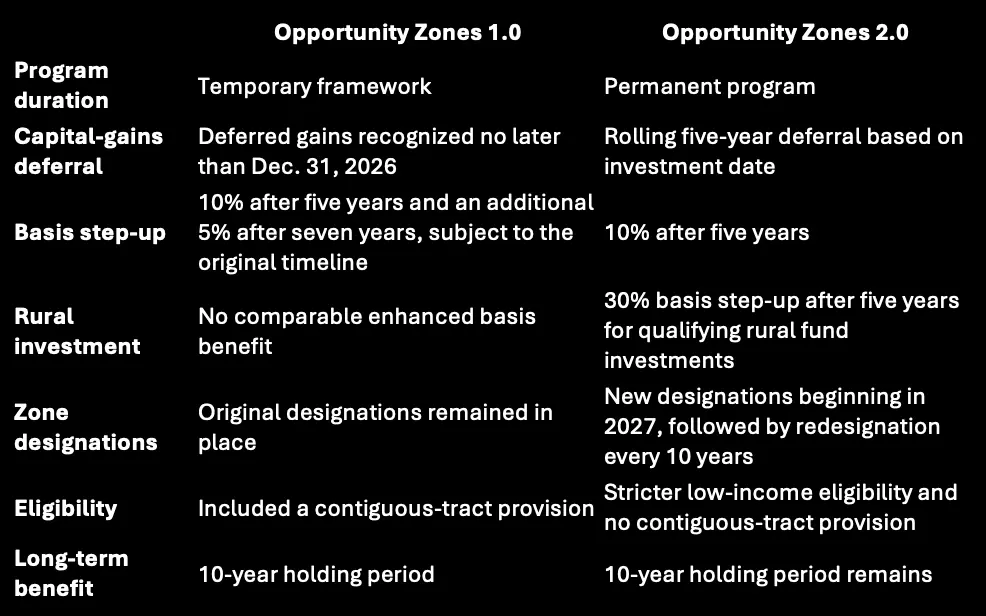
The first new round of Opportunity Zone designations takes effect January 1, 2027, beginning a recurring 10-year redesignation cycle. For investors evaluating Opportunity Zones ahead of 2027, five questions stand out.
OZ 2.0 replaces the program-wide 2026 recognition deadline with a five-year deferral period for qualifying investments made beginning in 2027. Deferred gains are generally recognized five years after the investment, unless an earlier inclusion event occurs.
Under OZ 1.0, deferred gains generally had to be recognized by December 31, 2026, regardless of when the investment was made, making the benefit progressively less valuable as the deadline approached.
Under OZ 2.0, each qualifying investment effectively receives its own five-year clock. Will Woodworth, senior vice president of investments at Peachtree Group, expects the change to allow better tax planning and support “more consistent cash flows into the space.”
Investors who hold a qualifying OZ 2.0 investment for at least five years receive a 10% basis step-up, while investments in a Qualified Rural Opportunity Fund (QROF) receive a 30% step-up after five years.
Under OZ 1.0, investors could receive a 10% increase after five years and another 5% after seven years, although the program’s fixed timeline limited those benefits for later investments.
OZ 2.0 also reduces the substantial-improvement threshold for property located entirely within qualifying rural Opportunity Zones from 100% to 50%. These incentives could make some rural projects more viable, but investors still need to independently underwrite demand, liquidity, financing and exit risk.
Yes. OZ 2.0 makes Opportunity Zones a permanent part of the tax code, with qualifying areas refreshed every 10 years.
Under OZ 1.0, investors faced an eventual program expiration and a fixed 2026 recognition date. Permanence allows investors, developers and capital allocators to evaluate Opportunity Zones as a long-term investment framework rather than an incentive approaching expiration.
As Woodworth put it, permanence makes Opportunity Zones an actionable strategy “not just right now, but for decades into the future.”
Yes. Under OZ 2.0, Opportunity Zones will be redesignated every 10 years, with the first new round taking effect in 2027. That differs from OZ 1.0, where the original map was essentially static.
Eligibility also becomes more targeted, with the qualifying median-family-income threshold declining from 80% to 70% and the contiguous-tract provision eliminated.
As a result, markets that qualified under OZ 1.0 may not qualify under OZ 2.0, while new eligible areas will emerge.
No. Investors generally still need to hold a qualifying Opportunity Zone investment for at least 10 years to access the program’s principal long-term tax benefit.
That remains an important consideration for real estate investors because a decade can span multiple property and credit cycles. Financing, valuations, supply and demand, and liquidity may look very different at exit than at acquisition.
The improved tax framework therefore does not change the importance of investment fundamentals, including basis, leverage, refinancing assumptions and sponsor execution.
OZ 2.0 also introduces a new 30-year rule worth noting. Under OZ 1.0, an investor only received the step-up to fair market value by selling the investment after the 10-year mark. Under OZ 2.0, that step-up to fair market value happens automatically at the 30-year point, regardless of whether the investor has sold.
Investors should first ask whether the underlying investment is attractive without the Opportunity Zone tax benefits.
The 2027 relaunch makes Opportunity Zones easier to evaluate as part of ongoing capital allocation rather than as a deadline-driven tax strategy. But the fundamental question remains:
Would this be an attractive investment without the tax benefit?
If the answer is no, a better Opportunity Zone structure may not change it. If the real estate, basis and capital structure are compelling, however, OZ 2.0 provides a more predictable framework for evaluating the after-tax return across multiple investment and real estate cycles.
This article is for informational purposes only and does not constitute tax, legal or investment advice.
Peachtree Group, a vertically integrated private investment firm active in commercial real estate, private credit and hospitality, today announced it has been named to the 2026 Inc. 5000, marking the firm’s fourth consecutive year on the magazine’s annual ranking of the fastest-growing private companies in the United States. Peachtree ranked 3,831 on this year’s list, with three-year revenue growth of approximately 67%.
Sustaining that pace is rare. Research from Stanford Graduate School of Business and IESE Business School found that only about 30% of companies on high-growth rankings return the following year, implying that roughly 3% would be expected to appear four successive years.
For Peachtree, the growth behind the ranking has also meant a larger team and a wider set of career paths. The firm has grown to over 3,700 employees across its investment, lending, development and hospitality businesses, with approximately 10% of open roles filled internally over the past year.
“We’re grateful for the recognition, but what I’m most proud of is the ecosystem behind it,” said Greg Friedman, managing principal and CEO of Peachtree. “We’ve built a place where someone can start in one division and build an entire career here, moving from real estate into credit, from underwriting into hotel operations, from analyst to principal, without ever having to leave. Growth on a list is a byproduct. Advancement in people’s careers is the point, and it’s the reason we’ve been able to maintain our expansion through different market environments.”
The recognition follows another milestone for the firm. Earlier this year, Peachtree was named to the inaugural PERE Credit 100, ranking among the world’s leading commercial real estate private credit managers. The annual ranking measures firms based on institutional capital raised for private real estate credit strategies over the previous five years.
“Together, these recognitions tell a consistent story,” Friedman added. “The Inc. 5000 acknowledges our ability to scale a high-growth business over time, and the PERE Credit 100 reflects the institutional platform we’ve built in commercial real estate credit. Both recognitions reveal the same foundation, a team that has earned the confidence of our investors and our partners.”
As investors increasingly seek tax-efficient strategies to preserve wealth and generate passive income, Peachtree Group ("Peachtree"), a leading commercial real estate investment firm, has expanded its Delaware Statutory Trust (DST) platform with two new acquisitions that provide accredited investors access to institutional-quality commercial real estate through 1031 exchange-eligible investment opportunities.
The expansion includes PG Cape Canaveral DST, anchored by the Holiday Inn Express Cape Canaveral in Florida, and PG St. Louis Industrial DST, a newly constructed Class A industrial facility in the St. Louis metropolitan area leased to Cummins Inc.
The acquisitions mark Peachtree's 14th and 15th DST offerings, bringing the total value of the firm's DST offerings to approximately $525 million since launching the platform in 2022. According to Mountain Dell Consulting, Peachtree currently ranks as the No. 7 most active 1031 exchange sponsor based on year-to-date 2026 capital raise activity.
"Our investors are looking for more than tax efficiency. They want access to high-quality real estate with durable income potential and professional management," said Greg Friedman, managing principal and CEO of Peachtree. "Our DST platform has been built to deliver institutional-quality investments across sectors where we have deep operating and investment expertise, giving investors access to opportunities that are often difficult to source on their own."
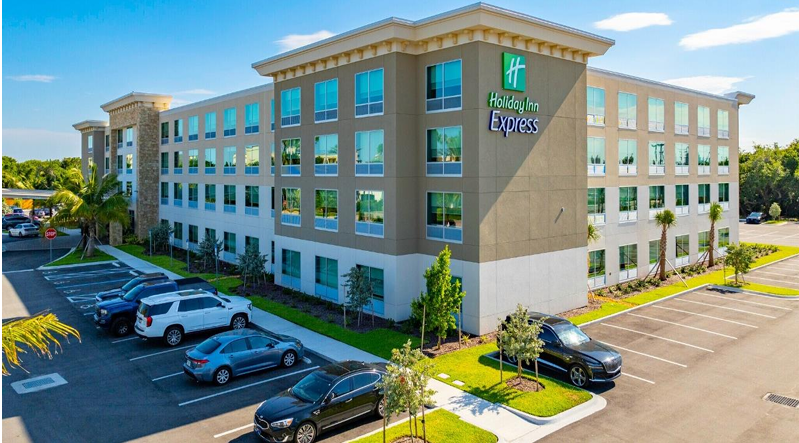
PG Cape Canaveral DST is anchored by the 150-room Holiday Inn Express Cape Canaveral, a recently developed hotel located directly across from Port Canaveral, the world's busiest cruise port. The property benefits from diversified demand generated by Port Canaveral, Kennedy Space Center, Cape Canaveral Space Force Station and Florida's Space Coast leisure destinations, creating multiple sources of lodging demand throughout the year.
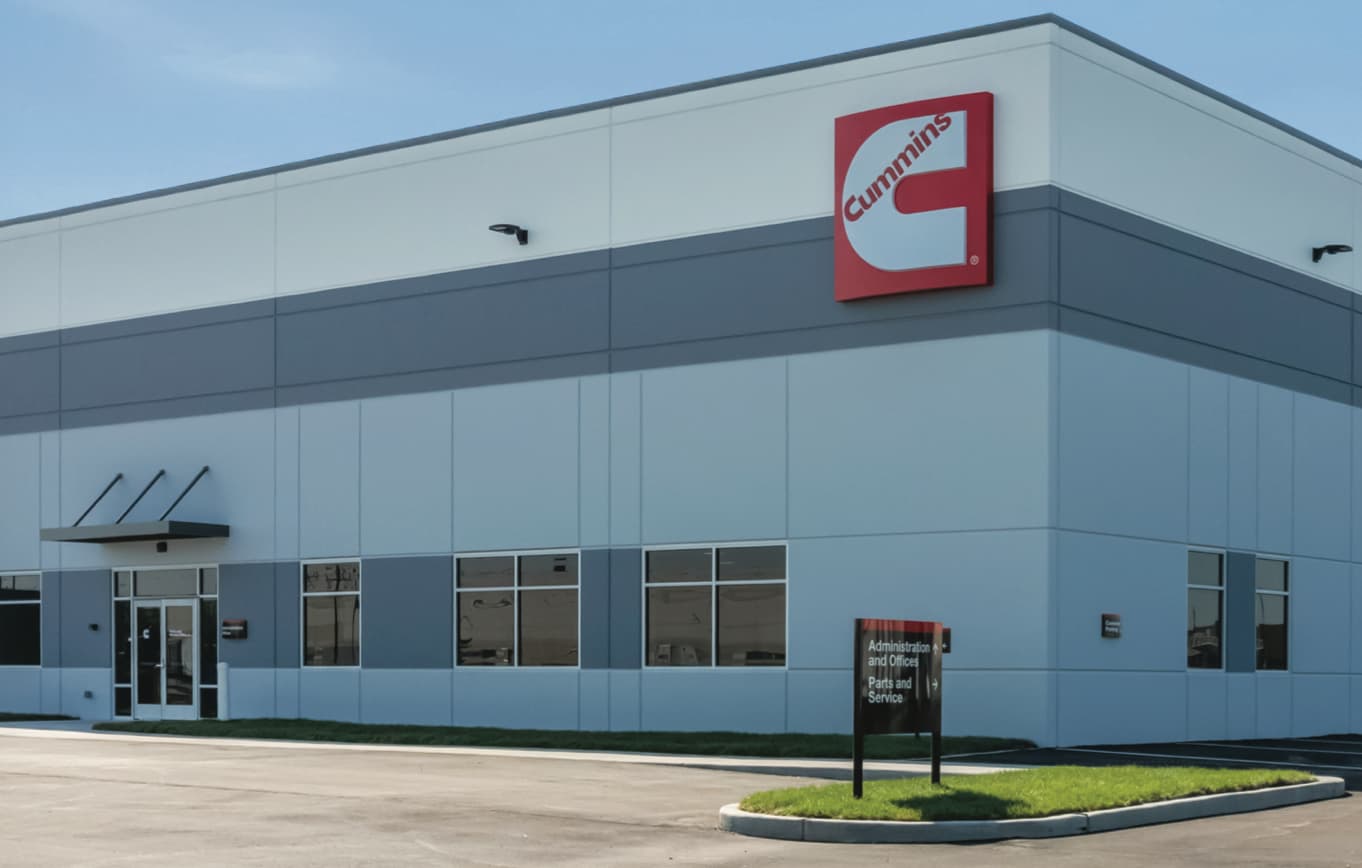
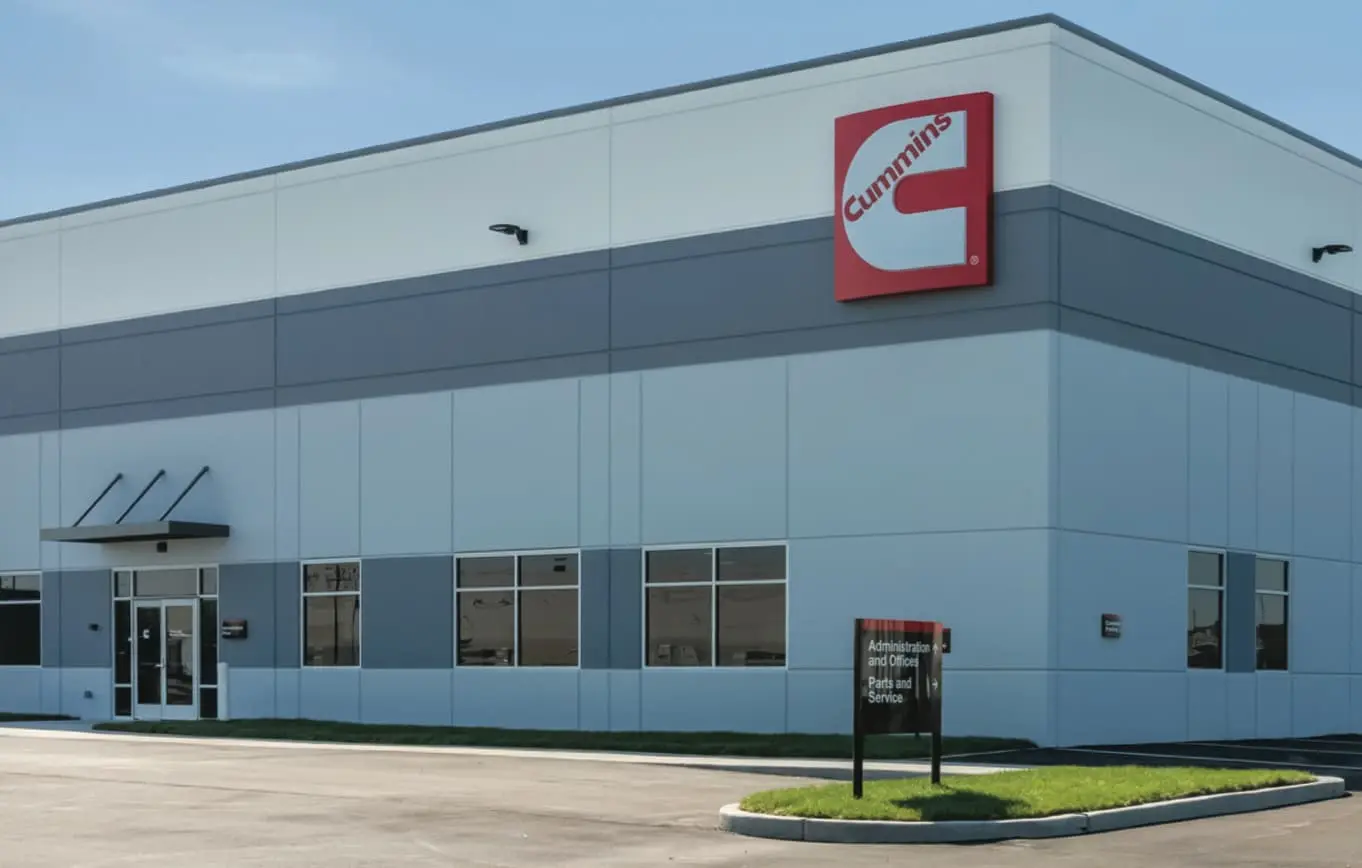
PG St. Louis Industrial DST consists of a newly constructed 48,206-square-foot Class A industrial sales and service facility in the St. Louis metropolitan area. The property is 100% leased under a 15-year net lease to Cummins Inc., an investment-grade global power solutions company. Located within Gateway Commerce Center, one of the nation's premier industrial parks, the asset offers stable cash flow supported by long-term corporate tenancy and contractual annual rent increases.
"We continue to expand our DST platform with investments that meet the same underwriting standards we apply across our broader real estate business," said Tim Witt, president of 1031 Exchange and DST Products at Peachtree. "By maintaining a disciplined approach to asset selection across multiple property sectors, we're building a broader pipeline of institutional-quality opportunities that help investors achieve their long-term investment objectives."
